2 ادعاءات قانونية مقبولة وموثقة لـ IT
Italy has binding national C&D CAM (Criteri Ambientali Minimi) for public procurement of construction services and works
Edilizia — Affidamento di servizi di progettazione e affidamento di lavori per interventi edilizi, adottati con DM 23 giugno 2022 n.256, pubblicato in G.U. n.183 del 6 agosto 2022. Decreto correttivo 5 agosto 2024 del Ministero dell'Ambiente e della Sicurezza Energetica «Modificazioni al decreto n.256 del 23 giugno 2022, recante: Criteri ambientali minimi per l'affidamento di servizi di progettazione e affidamento di lavori per interventi edilizi»
Italian contracting authorities must apply CAM Edilizia environmental criteria when awarding C&D-related construction works and design services above relevant thresholds
ARRR — Agenzia Regionale Recupero Risorse è una società in house della Regione Toscana che lavora a supporto delle politiche regionali in tema di rifiuti ed energia. Opera in materia di prevenzione della produzione di rifiuti, del loro riciclo e recupero
1 ادعاء قانوني مقبول وموثق لـ IT
Abandonment / deposit of waste or discharge into surface/groundwater under D.Lgs. 152/2006 Art. 255(1), as amended through the 2025 reform (DL 116/2025 + conversion law) — criminal fine tier
D.Lgs. 152/2006 Art. 255(1): sanctions for abandonment / uncontrolled deposit of waste — fine range, as amended through DL 116/2025 + conversion law.
3 ادعاءات قانونية مقبولة وموثقة لـ IT
Piano Transizione 5.0: credito d'imposta for new investments from 01/01/2024 to 31/12/2025 in production sites in Italy, in innovation projects reducing energy consumption ≥3%
il credito d'imposta per le imprese che effettuano nuovi investimenti, a decorrere dal 1° gennaio 2024 e fino al 31 dicembre 2025, destinati ad aziende ubicate nel territorio dello Stato, nell'ambito di progetti di innovazione che comportano una riduzione dei consumi energetici della struttura produttiva non inferiore al 3 per cento. Quote d'investimento fino a 10 milioni di euro: 35%/40%/45% by reduction band; oltre 10 milioni: 5%/10%/15%
Piano Transizione 5.0: maggiorazione 30% for purchase of photovoltaic panels with type a) modules; 40% type b); 50% type c)
ha ridefinito lo schema delle maggiorazioni, introducendo una maggiorazione del 30% per l'acquisto di pannelli fotovoltaici con moduli di tipo a) e incrementando al 40% e al 50% le maggiorazioni per i pannelli fotovoltaici con moduli di tipo b) e c)
Piano Transizione 5.0: credito d'imposta on competenze utili alla transizione dei processi produttivi limited to 10% of investments in beni strumentali, max €300,000
di competenze utili alla transizione dei processi produttivi (nel limite del 10% degli investimenti effettuati nei beni strumentali e nel limite massimo di 300 mila euro)
2 ادعاءات قانونية مقبولة وموثقة لـ IT
Italy's national framework for tributo speciale per il conferimento dei rifiuti speciali in discarica established by L.549/1995 (Finanziaria 1996) art.3 cc.24-41 — sets framework, but regional councils set the actual rate per kg annually by 31 July
Per effetto della Legge n.549/95 (Finanziaria per l'anno 1996), art.3, commi da 24 a 41, è stato istituito il tributo speciale per il conferimento dei rifiuti speciali in discarica. La legge – oggi ancora vigente riferimento normativo nazionale – è stata oggetto di recepimento in pressoché tutte le regioni, con provvedimenti di L.R. L'ammontare dell'imposta è fissato, con legge della Regione entro il 31 luglio di ogni anno per l'anno successivo, per chilogrammo di rifiuti conferiti.
Regione Piemonte tributo speciale discarica rates effective 01/01/2024: €0.01/kg for inert waste; €0.02582/kg for non-hazardous waste — set under LR 1/2018 art.15 c.1 lett.c
in vigore dal 1° gennaio 2024 ... si applicano gli importi di cui all'articolo 15, comma 1, lettera c, della legge regionale n.1/2018: 0,01 euro per ogni chilogrammo per i rifiuti ammissibili al conferimento in discarica per rifiuti inerti; 0,02582 euro per ogni chilogrammo per i rifiuti ammissibili al conferimento in discarica per rifiuti non pericolosi
▸ التفويض التنظيمي“Italy's Environmental Code (D.Lgs. 152/2006) Art. 181 comma 4 lettera b) sets a 70% preparation-for-reuse/recycling/recycling target for non-hazardous construction and demolition waste. No national statutory gate fee exists — gate fees are commercial/market-based and are not published in canonical data. Enforcement is shared: MASE (Ministero dell'Ambiente e della Sicurezza Energetica) is the framework authority per Art. 1; regional and ATO authorities hold waste-management competence per Art. 181; unauthorized waste management is sanctioned criminally per Art. 256/259. EU Waste Framework Directive 2008/98/EC is transposed via D.Lgs. 152/2006 Part IV.”
Regional Landfill Gate Fees normalized to $/ST for US/Global baseline comparisons. Local operating calculations utilize local EUR/t rate structures.
إعداد رسوم المكب غير متوفر — البيانات مفقودة.
Italy's Environmental Code (D.Lgs. 152/2006) Art. 181 comma 4 lettera b) sets a 70% preparation-for-reuse/recycling/recycling target for non-hazardous construction and demolition waste. No national statutory gate fee exists — gate fees are commercial/market-based and are not published in canonical data. Enforcement is shared: MASE (Ministero dell'Ambiente e della Sicurezza Energetica) is the framework authority per Art. 1; regional and ATO authorities hold waste-management competence per Art. 181; unauthorized waste management is sanctioned criminally per Art. 256/259. EU Waste Framework Directive 2008/98/EC is transposed via D.Lgs. 152/2006 Part IV.
| المعامل | القيمة |
|---|---|
| المنطقة | إيطاليا |
| رسوم المكب | — |
| الإنتاجية السنوية | 40,000 t/yr |
| معدل التحويل عن المكب | 80% |
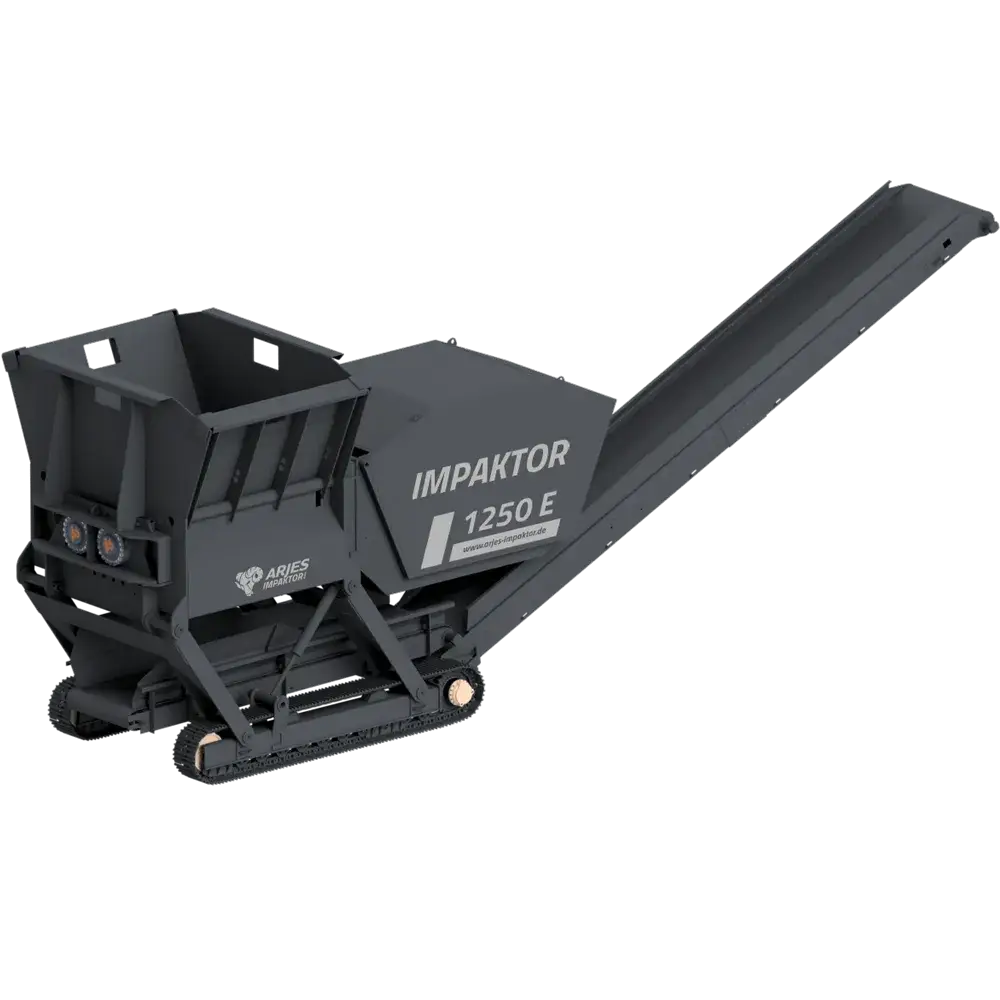
| النظام الموصى به | IMPAKTOR 1250 E |
| نوع الناقل | ELECTRIC |
| معيار الانبعاثات | NOT APPLICABLE |
| مكون OPEX | التكلفة السنوية (EUR) |
|---|---|
| ديزل + AdBlue | €207,391 |
| الصيانة | €14,000 |
| إجمالي OPEX السنوية | €221,391 |