NL 的 2 项已接受并验证的规范声明
Wet milieubeheer (BWBR0003245) is the primary Dutch national environmental law, retained alongside the Omgevingswet and containing Hoofdstuk 10 Afvalstoffen (articles 10.1-10.64) as the waste framework.
wetten.overheid.nl page title: 'Regeling - Wet milieubeheer - BWBR0003245'. Header: 'Geraadpleegd op 09-09-2026. Geldend van 01-08-2026 t/m heden.' ToC: 'Hoofdstuk 10 Afvalstoffen (Artikelen 10.1-10.64)' including 'Titel 10.2 Het circulair materialenplan (Artikelen 10.3-10.14)'.
Omgevingswet (BWBR0037885) entered into force on 1 January 2024 and is the umbrella environmental activities framework replacing parts of Wet milieubeheer for activities/permits.
wetten.overheid.nl page title: 'Regeling - Omgevingswet - BWBR0037885'. Header: 'Geraadpleegd op 09-09-2026. Geldend van 01-07-2026 t/m heden.' ToC: 'Hoofdstuk 1 Algemene bepalingen (Artikelen 1.1-1.8)', references to 'verplichte instructieregels Rijk stedelijk afvalwater', etc.
NL 的 3 项已接受并验证的规范声明
Besluit bouwwerken leefomgeving article 7.24 imposes an obligation that construction and demolition work must be performed in such a way that hazardous and other C&D waste arising during execution is properly separated (deugdelijk wordt gescheiden).
Artikel 7.24 body: 'Bouw- en sloopwerkzaamheden worden zodanig verricht dat tijdens de uitvoering vrijkomend gevaarlijk en overig bouw- en sloopafval deugdelijk wordt gescheiden.' § 7.1.5 'Scheiden bouw- en sloopafval (Artikelen 7.24-7.26)'.
BBL article 7.25 requires separation of hazardous C&D waste into at least 4 fractions: (a) hazardous waste designated per Regeling Europese afvalstoffenlijst chapter 17 (not in b-d); (b) tar-containing roofing; (c) tar-containing asphalt; (d) gas discharge lamps. Hazardous substances must not be mixed or further separated. Fractions must be kept separated on the construction/demolition site and removed separately (with documented exception allowing off-site separation when on-site separation is reasonably not possible).
Besluit bouwwerken leefomgeving Artikel 7.25 lid 1: 'Ongeacht de hoeveelheid wordt gevaarlijk bouw- en sloopafval in ieder geval gescheiden in de volgende fracties: a. als gevaarlijk aangeduide afvalstoffen als bedoeld in hoofdstuk 17 van de Regeling Europese afvalstoffenlijst; b. teerhoudende dakbedekking; c. teerhoudend asfalt; d. gasontladingslampen.'
BBL article 7.26 requires separation of other (non-hazardous) C&D waste into at least 6 fractions: (a) bituminous roofing; (b) non-tar asphalt; (c) flat glass (with/without frame); (d) gypsum blocks and plasterboard; (e) roof gravel; (f) luminaires. Fractions must be kept separated on the construction/demolition site and removed separately. De-minimis: paragraphs 1 and 2 do not apply where the quantity of waste of that fraction is less than 1 m³.
Besluit bouwwerken leefomgeving Artikel 7.26 lid 1: 'Overig bouw- en sloopafval wordt in ieder geval gescheiden in de volgende fracties: a. bitumineuze dakbedekking; b. niet-teerhoudend asfalt; c. vlakglas; d. gipsblokken en gipsplaatmateriaal; e. dakgrind; f. armaturen.' lid 3: niet van toepassing als fractie minder dan 1 m³ bedraagt.
NL 的 2 项已接受并验证的规范声明
Wet op de economische delicten (WED, BWBR0002063) is the Dutch Economic Offences Act, article 1 of which lists categories of economic offences (overtredingen van voorschriften) including violations of environmental statutes such as Wet milieubeheer, Omgevingswet, Drinkwaterwet, Mijnbouwwet, etc.
wetten.overheid.nl page title: 'Regeling - Wet op de economische delicten - BWBR0002063'. Header: 'Geraadpleegd op 09-09-2026. Geldend van 01-08-2026 t/m heden.' ToC: 'Titel I Van de economische delicten (Artikelen 1-4)', 'Titel II Van de straffen en maatregelen (Artikelen 5-16)'. Article 1 body: 'Economische delicten zijn: 1°. overtredingen van voorschriften, gesteld bij of krachtens: ...' with extensive list of statutes.
Wetboek van Strafrecht article 23(4) lists 6 categories of geldboete (fines). Pre-2026 maxima: 1e €335, 2e €3.350, 3e €6.700, 4e €16.750, 5e €67.000, 6e €670.000. From 1 January 2026: 1e €550, 2e €5.500, 3e €11.000, 4e €27.500, 5e €110.000, 6e €1.100.000.
Wetboek van Strafrecht BWBR0001854 article 23(4): 'Er zijn zes categorieën: 1e categorie € 335 [Per 1-1-2026: € 550]; 2e € 3.350 [€ 5.500]; 3e € 6.700 [€ 11.000]; 4e € 16.750 [€ 27.500]; 5e € 67.000 [€ 110.000]; 6e € 670.000 [€ 1.100.000].'
NL 的 3 项已接受并验证的规范声明
Energie-investeringsaftrek (EIA) for 2025 and 2026 = 40% of the investment in new company assets on the Energielijst, with a minimum of €2,500 per asset; the asset must not have been previously used.
Belastingdienst EIA page body: 'In 2025 en 2026 is de EIA 40% van de investering die u hebt gedaan. Voorwaarden: U komt in aanmerking voor de EIA als uw investering in een bedrijfsmiddel voldoet aan de volgende 3 voorwaarden: Het bedrag aan energie-investeringen is minimaal € 2.500 per bedrijfsmiddel. Het bedrijfsmiddel is niet eerder gebruikt.'
Milieu-investeringsaftrek (MIA) allows businesses to deduct up to 45% of the investment amount from profit. The exact deduction percentage depends on the environmental impact and the prevalence of the asset (indicated by a letter code in the Milieulijst published by RVO).
Belastingdienst MIA/VAMIL page body: 'Met de milieu-investeringsaftrek biedt u de mogelijkheid de fiscale winst te verlagen. U kunt tot 45% van het investeringsbedrag in mindering brengen op de winst. Het percentage van de aftrek is afhankelijk van de milieu-effecten en de gangbaarheid van het bedrijfsmiddel.'
Willekeurige afschrijving milieu-investeringen (VAMIL) allows businesses to depreciate an environmental investment at an arbitrary point in time (i.e. accelerated depreciation), reducing the fiscal profit in the chosen year. VAMIL is administered alongside MIA via the Milieulijst published by RVO.
Belastingdienst MIA/VAMIL page body: 'VAMIL. Met de VAMIL kunt u een investering op een willekeurig moment afschrijven. Door sneller afschrijven vermindert u de fiscale winst.'
NL 的 2 项已接受并验证的规范声明
Wet belastingen op milieugrondslag (BWBR0007168) article 28 sets the Afvalstoffenbelasting (national waste disposal tax) tariff at €40.85 per 1,000 kilogram for: (a) storten (landfill); (b) verbranden (incineration) in general; (d) overbrenging (transfer). Tariff is nihil (zero) for incineration in installations that are not permitted to accept household/mixed commercial waste (case c).
Wet belastingen op milieugrondslag BWBR0007168 article 28 lid 1: 'Het tarief bedraagt in geval van: a. het storten van afvalstoffen: € 40,85 per 1.000 kilogram; b. het verbranden van afvalstoffen in andere gevallen: € 40,85 per 1.000 kilogram; d. de overbrenging van afvalstoffen: € 40,85 per 1.000 kilogram.'
CO2-heffing on waste incineration installations (afvalverbrandingsinstallaties) under Wet belastingen op milieugrondslag scales per 1,000 kg CO2 emissions from €87,90 (2025) → €100,70 (2026) → €113,60 (2027) → €126,40 (2028) → €139,30 (2029) → €152,10 (2030 and thereafter) under current agreements. Government proposal would raise the 2027-2030 schedule to €149,30 / €197,90 / €246,40 / €295.
Rijksoverheid page: 'Vanaf 1 januari 2027 betalen afvalverbrandingsinstallaties meer CO2-belasting. De tarieven per 1000 kilo CO2-uitstoot lopen elk jaar op. Vanaf 2030 is het tarief dan € 295.' Table: 'CO2-heffing 2025 2026 2027 2028 2029 2030 en daarna — Nu geldende afspraken: € 87,9 € 100,7 € 113,6 € 126,4 € 139,3 € 152,1 — Voorstel CO2-heffing afvalverbrandingsinstallaties: € 87,9 € 100,7 € 149,3 € 197,9 € 246,4 € 295.'
NL 的 2 项已接受并验证的规范声明
Uitvoeringsbesluit EU-verordening emissiegrenswaarden voor motoren in niet voor de weg bestemde mobiele machines (BWBR0041089) is the Dutch national implementing act for EU Regulation 2016/1628 on NRMM engine emission limits and type-approval; Geldend van 19-04-2023 t/m heden. Besluit van 19 juni 2018 (Staatsblad 2018, 201).
wetten.overheid.nl BWBR0041089 — 'Uitvoeringsbesluit EU-verordening emissiegrenswaarden voor motoren in niet voor de weg bestemde mobiele machines' — Geldend van 19-04-2023 t/m heden; cites Verordening (EU) 2016/1628 van 14 september 2016 (Stage V NRMM).
Regulation (EU) 2016/1628 of the European Parliament and of the Council of 14 September 2016 establishes emission limits for gaseous and particulate pollutants and type-approval for internal combustion engines for non-road mobile machinery (NRMM), including Stage V emission limits. It is directly applicable in NL and implemented nationally via BWBR0041089.
EUR-Lex Regulation (EU) 2016/1628 of the European Parliament and of the Council of 14 September 2016 — Article 1: 'This Regulation establishes for all engines referred to in Article 2(1) emission limits for gaseous and particulate pollutants as well as the administrative and technical requirements relating to EU type-approval.' Recital 38 references Stage V.
NL 的 1 项已接受并验证的规范声明
Klimaatwet (BWBR0042394) article 2 sets a binding national TARGET: net greenhouse gas emissions reduced to zero by 2050, with intermediate target of 55% reduction vs 1990 by 2030 and 100% CO2-neutral electricity production by 2050. This is a TARGET law, not an equipment-level zero-emission mandate for NRMM/construction equipment.
Klimaatwet BWBR0042394 article 2 lid 1: 'a. de netto-uitstoot van broeikasgassen uiterlijk in 2050 tot nul reduceert; b. streeft naar negatieve emissies na 2050.' lid 2: 'een reductie van broeikasgassen van 55% ten opzichte van 1990 in 2030 en CO2-neutrale elektriciteitsproductie in 2050.' Geldend 01-01-2026.
规范 — 已验证来源 — 法律框架
Regional Landfill Gate Fees normalized to $/ST for US/Global baseline comparisons. Local operating calculations utilize local EUR/t rate structures.
填埋费预设不可用——缺少数据。
| 参数 | 数值 |
|---|---|
| 区域 | 荷兰 |
| 垃圾填埋费 | — |
| 处理量 | 40,000 t/yr |
| 分流率 | 80% |
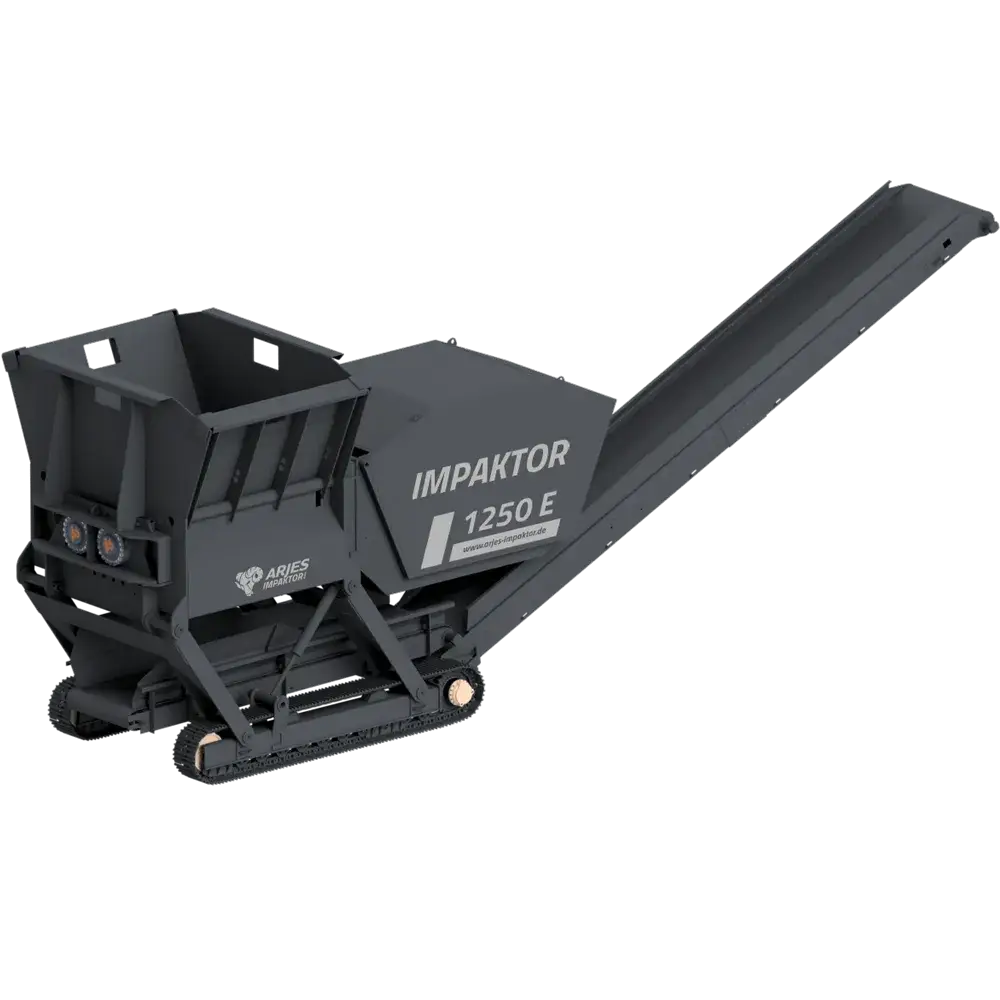
| 推荐系统 | ARJES Impaktor 1250 E |
| 驱动类型 | ELECTRIC |
| 排放标准 | NOT APPLICABLE |
| 运营支出组件 | 运营支出成本 |
|---|---|
| 电力 | €196,386 |
| 维护 | €14,000 |
| 总计 | €210,386 |